Calgary September 2026 Market Trends
Detached Homes Are Bucking the Trend — Everything Else Needs a Closer Look
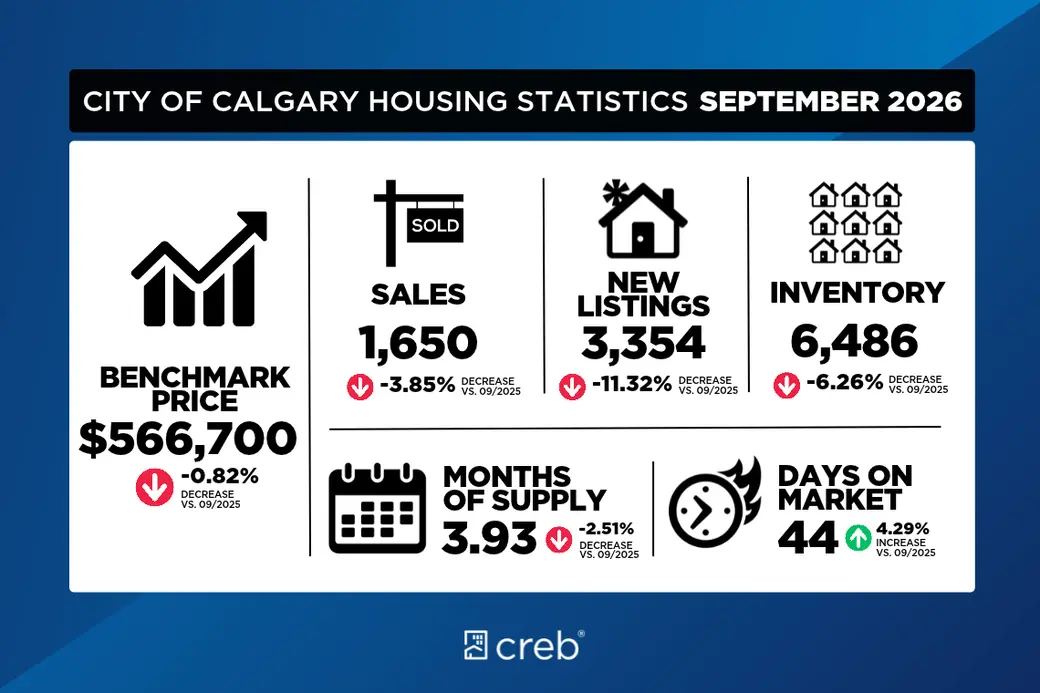
September sales held steady with August and came in just 4% below last year — with detached homes actually gaining ground year-over-year. The two-speed market continues.
Hi there,
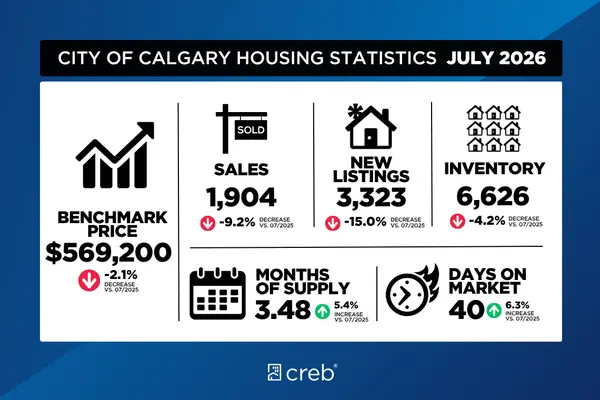
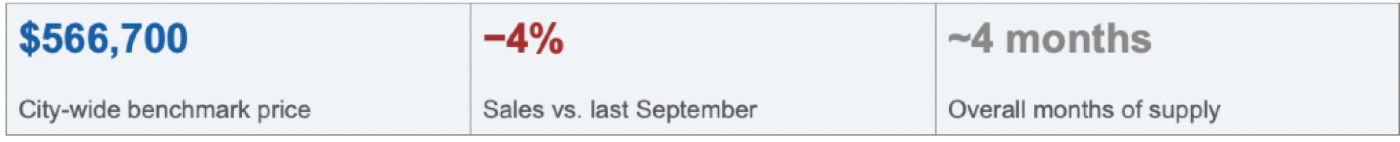
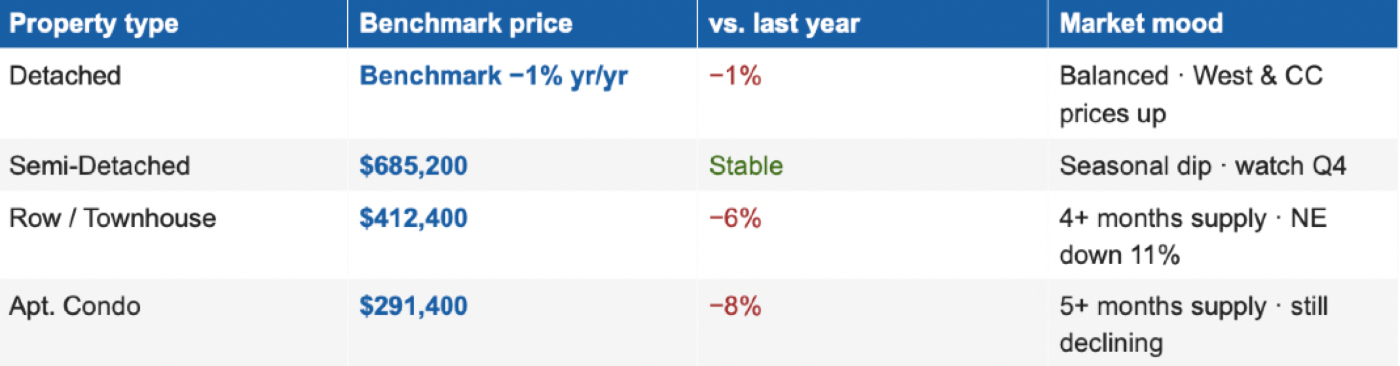
September delivered a market that looks calm on the surface — 1,650 sales, nearly identical to August — but underneath, the detached segment is quietly outperforming, while apartment condos and row homes continue to feel the weight of excess supply. The city-wide benchmark price of $566,700 is down just 1% from last September, but that number tells very different stories depending on what you're buying or selling.
The bright spot: detached sales are actually up
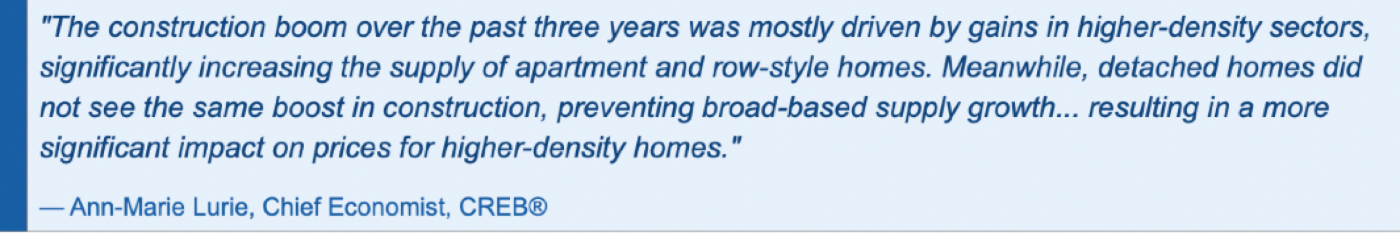
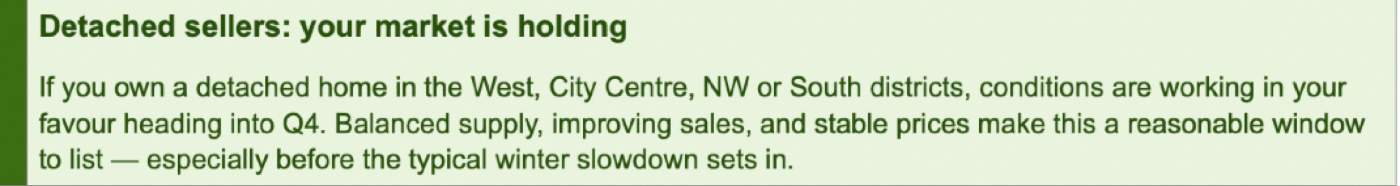
Here's the headline that got buried in the overall numbers: detached home sales in September were up more than 4% compared to last year. That's a meaningful shift. A boost in new listings gave buyers more to choose from, and they responded. With just over 3 months of supply city-wide, the detached market remains in balanced territory — and in the North West, West and South districts, supply is under 3 months, which is firmly seller-friendly.
Prices in the West district and City Centre are still tracking above last year's levels. The drag on detached prices is coming primarily from the North East district, where oversupply is creating buyer market conditions and pulling the city-wide average down.
Prices by property type — September 2026
What to watch: semi-detached shift
One thing worth noting this month: the semi-detached sector saw its months of supply push to nearly 4 months — a shift from the tighter conditions it's enjoyed for most of 2026. A surge in September listings caused the sales-to-new-listings ratio to dip to 45%. One month doesn't make a trend, but it's worth watching as we move into Q4. Prices dipped but are still comparable to last September overall.
Around the region
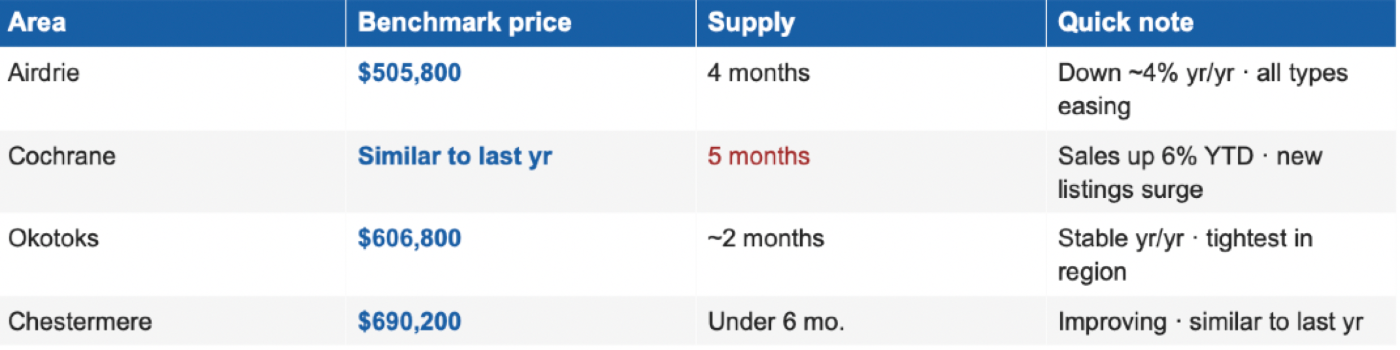
Okotoks remains the standout — even with a slight dip in its sales-to-listings ratio (76%), conditions are still the tightest in the region at just over 2 months of supply. Prices are holding within 1% of last year. Cochrane's September was one to watch — the sales-to-new-listings ratio dropped to 42%, the lowest since January, partly driven by new home listings making up 30% of total listings. Months of supply hit 5. That said, year-to-date sales are still up 6% and prices are holding near last year's levels. Chestermere is showing signs of improvement — months of supply came back below 6 and prices are only 1% off last year despite the challenging conditions earlier in the year.
Looking ahead to Q4
A few things will shape how the fall market closes out:
- Detached momentum is the story to watch. If new listings stay elevated and buyers keep showing up, we could see balanced-to-seller conditions persist in key districts through October and November.
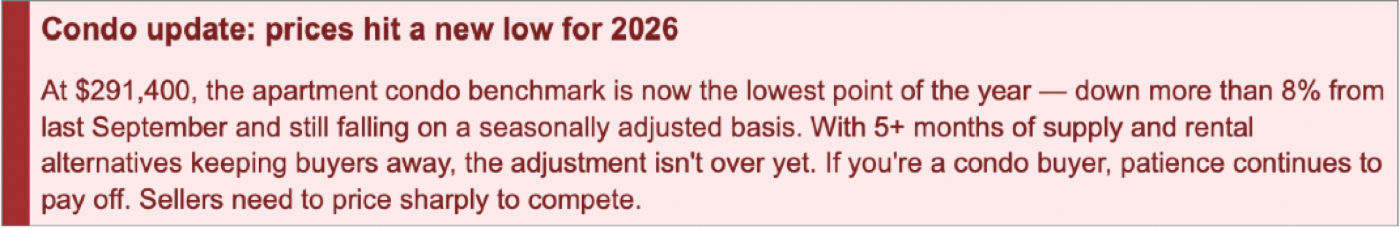
- Condo and row supply isn't going anywhere fast. With 5+ months of condo supply and prices still adjusting, the buyer advantage in higher-density homes will extend well into Q4 and likely into 2027.
- Seasonal price dips are normal in fall. The unadjusted numbers will look softer in October and November — that's typical. Seasonally adjusted figures tell the more accurate story of where the market truly stands.
- Your district is everything. Whether buying or selling, the city-wide number is a rough average of very different realities. West district detached and North East detached are not the same market — and knowing the difference is where we add real value.
As always, we're here to help you navigate what these numbers actually mean for your situation — not just the headlines.
Warm regards,
Raj and Sukh Dhaliwal
The Bijou Real Estate Team
Categories
Recent Posts